What Drove the Spike in Early Social Security Claims, and What It Means for Florida's 5.3 Million Beneficiaries
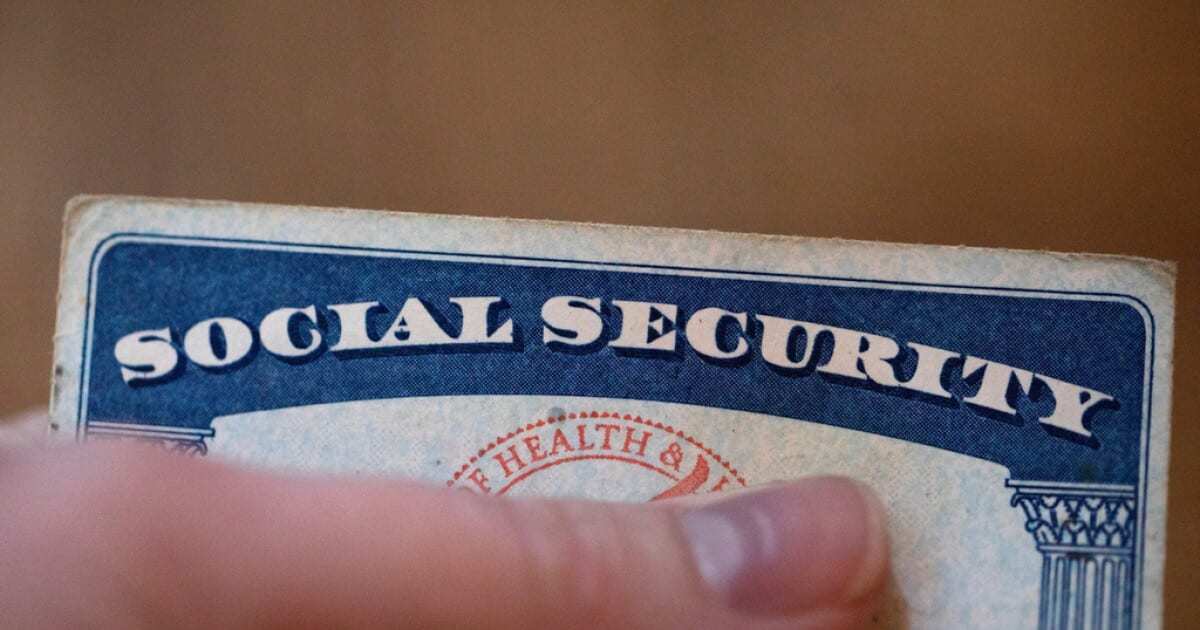
A sudden jump in Americans filing for Social Security in 2025, followed by an almost equally sharp drop this year, has researchers pointing to turmoil at the Social Security Administration and fear about the program's future as the drivers. The swing matters in Florida, where about 5.3 million people collect Social Security benefits, including roughly 4.2 million retired workers, and where the decision of when to claim can mean thousands of dollars a year for the rest of a retiree's life.
The findings, reported by KFF Health News and published by WUSF on Nov. 19, draw on work by the Urban Institute and the Center for Retirement Research at Boston College.
The surge and the reversal
Urban Institute researchers, including senior policy fellow Jack Smalligan, found that from October 2024 to April 2025, new Social Security claims rose by 267,000 compared with the year before, a 13% increase. Typical year-to-year fluctuations had been around 2% to 3%. Population growth and adjustments for a small group of public employees did not explain the jump, according to the researchers.
Then the trend flipped. From October 2025 to April 2026, new claims fell by 235,000, or about 10%. Smalligan described the drop as almost an exact reversal of the surge.
The swing broke with a long-running pattern. Before 2025, economists had documented that Americans were retiring and claiming benefits later. Most people still claim before their full retirement age, which is 67 for anyone born in 1960 or later, but the share claiming at the earliest age, 62, had been falling.
What researchers say caused it
Smalligan attributed the 2025 surge to turmoil at the Social Security Administration. KFF Health News cited the Trump administration's Department of Government Efficiency, false claims of widespread fraud, mass staff cuts, threats to close field offices and Elon Musk's onstage chainsaw stunt at a February 2025 conference. Musk also called Social Security "the biggest Ponzi scheme of all time."
Earlier research supports the idea that alarming headlines push people to claim sooner. A 2021 Center for Retirement Research study led by Gal Wettstein asked more than 3,100 participants to read Social Security headlines. Those who read fear-inducing headlines said they would claim benefits about a year earlier than those who read neutral ones.
The Social Security Administration said it is providing the best customer service in its history. The agency did not respond to KFF Health News' questions about the reasons for the claims spike. Smalligan said people continue to have difficulty reaching the agency by phone or in person and noted that its administrative budget has been underfunded for years.
The long shift toward claiming later
The Center for Retirement Research's analysis shows how far claiming behavior had moved before the 2025 disruption. The following table compares the share of men and women claiming at 62 and at 67 or later.
| Group | 2019 | 2023 |
|---|---|---|
| Men claiming at 62 | 31% | 26% |
| Women claiming at 62 | 34% | 27% |
| Men claiming at 67 or later | 19% | 26% |
| Women claiming at 67 or later | 20% | 25% |
The trend toward later claiming continued into 2024, according to the center. Alicia Munnell, the center's former director, pointed to the 1983 changes to Social Security law that created incentives to work longer. Other factors include employers' move from traditional pensions to 401(k) plans, the decline of retiree health insurance, less physically demanding work and improvements in health and longevity.
Why the timing decision is so costly
Claiming at 62 locks in a permanently lower monthly check. Waiting past full retirement age raises benefits by 8% for each year of delay until age 70, which Smalligan described as an inflation-protected annuity. Delaying also increases the survivor benefit available to a spouse.
The personal stakes show up in the stories KFF Health News collected. A former museum exhibit designer in Delaware who lost his job in 2022 claimed at 64, reducing his benefits by about $5,000 a year. A nuclear medicine technologist in New York who stopped working more than a year before her full retirement age gave up about $300 a month and now works one day a week at a hospital.
People who claimed at or after full retirement age but before 70 can suspend their benefits and restart them later at a higher amount.
The Florida stakes
Florida has a large stake in claiming decisions. As of December 2025, 5,294,001 Floridians received Social Security benefits, including 4,191,491 retired workers, according to Social Security Administration state data. The rest are spouses, children, survivors and disabled workers.
The average Social Security benefit in Florida was about $1,962 a month in 2025, according to a Kiplinger analysis of the agency's Annual Statistical Supplement. Nationally, the average retired worker's check is expected to rise from about $2,095 to about $2,170 a month in January, after the Social Security Administration announced a 3.6% cost-of-living adjustment for 2027 on Oct. 14. That increase is the largest since 2023 and follows a 2.8% adjustment for 2026.
Because cost-of-living adjustments are applied as a percentage of a retiree's benefit, anyone who claimed early out of worry about the program's future accepted not only a smaller check, but smaller dollar increases in every year that follows.
The solvency question
Underlying the anxiety is a real deadline. The 2026 Social Security trustees' report projects that the retirement trust fund will be depleted in late 2032 without action by Congress. Benefits would still be paid after that, but could be up to 22% lower.
Sens. Elizabeth Warren, a Massachusetts Democrat, and Bernie Moreno, an Ohio Republican, are preparing bipartisan legislation that would apply the payroll tax to wages above the current cap of $184,500, KFF Health News reported. The trustees estimate that change would raise $3 trillion over 10 years. A solvency plan from the Brookings Institution also proposes lifting the cap.
What's next
The 3.6% cost-of-living adjustment will appear in most checks starting in January 2027. Researchers will be watching whether the drop in new claims this year holds, and whether Congress acts on solvency before the 2032 depletion date. For Floridians approaching 62, the research offers a plain lesson: the age at which they claim is usually permanent, and headlines about the program's future have been shown to push people toward a choice they cannot easily reverse.
Spotted an issue with this article?
Have something to say about this story?
Write us a letterComments
No comments yet. Be the first to weigh in.
Related Coverage
U.S. and Venezuela Sign Deal to Restore Military Ties as Hegseth Visits Caracas, a Shift Felt in Doral
54m ago
HUD Will Screen FHA Mortgage Applicants for Delinquent Child Support Starting March 2027
4h ago
Florida Pastor Christian Sanon Convicted in Miami in Plot Tied to Assassination of Haiti's President
6h ago
Federal Judge Rules Florida's Form 6 Financial Disclosure Law for Local Officials Unconstitutional
7h ago