Florida's Insurance Recovery Is Real, and It Rests Entirely on Storms That Have Not Come
Florida's property insurance market is measurably better than it was three years ago. State regulators have approved a string of homeowners rate decreases through 2026, including four more averaging about 7 percent across roughly 62,000 policies. Citizens Property Insurance has shrunk to fewer than 255,000 policies from about 1.4 million in September 2023. Citizens itself won approval for an 8.7 percent statewide average decrease, its first since 2015.
Those are real numbers, and the people who argued that the 2022 and 2023 litigation reforms would improve the market have a legitimate claim to having been right about direction. What they have not yet earned is the conclusion that the problem is solved, because the single largest variable in Florida insurance pricing has been quiet, and quiet is not the same as durable.
Florida has not absorbed a direct major hurricane landfall into a densely insured metropolitan area during this recovery. That is the test the current market has not taken, and until it does, every favorable figure in the state's filings rests on a run of weather rather than on a structure that has been proven to hold.
What actually changed
Three things moved at once, and separating them matters for judging durability. The Legislature changed how attorney fees are awarded in property insurance disputes, tightened assignment of benefits rules and shortened claim filing windows. Reinsurance costs, which spiked after 2022, moderated. And capital returned to the state, licensing new carriers and funding expansion at existing ones.
Only the first is permanent in the sense that it stays put unless the Legislature changes it back. Reinsurance pricing is set annually in a global market that reprices after catastrophe losses anywhere in the world, not just in Florida. Carrier capital is the most mobile of the three and leaves faster than it arrives.
That means the reforms supporters credit and the market improvement critics doubt are not the same thing. The legal changes reduced a specific cost driver. The rate decreases reflect that reduction plus two factors that can reverse within a single renewal cycle.
The honest framing is that Florida fixed one structural problem and got lucky on two cyclical ones simultaneously. Distinguishing those is not a partisan point. It is the difference between a market that can absorb a bad year and one that merely has not had one.
Why the storm test is the only test that counts
Florida insurance is a catastrophe business, which makes it different from auto or health coverage in a way that is easy to lose sight of during calm years. A carrier's ordinary claims experience tells you very little about whether it survives. What matters is whether its surplus plus its reinsurance covers a single tail event.
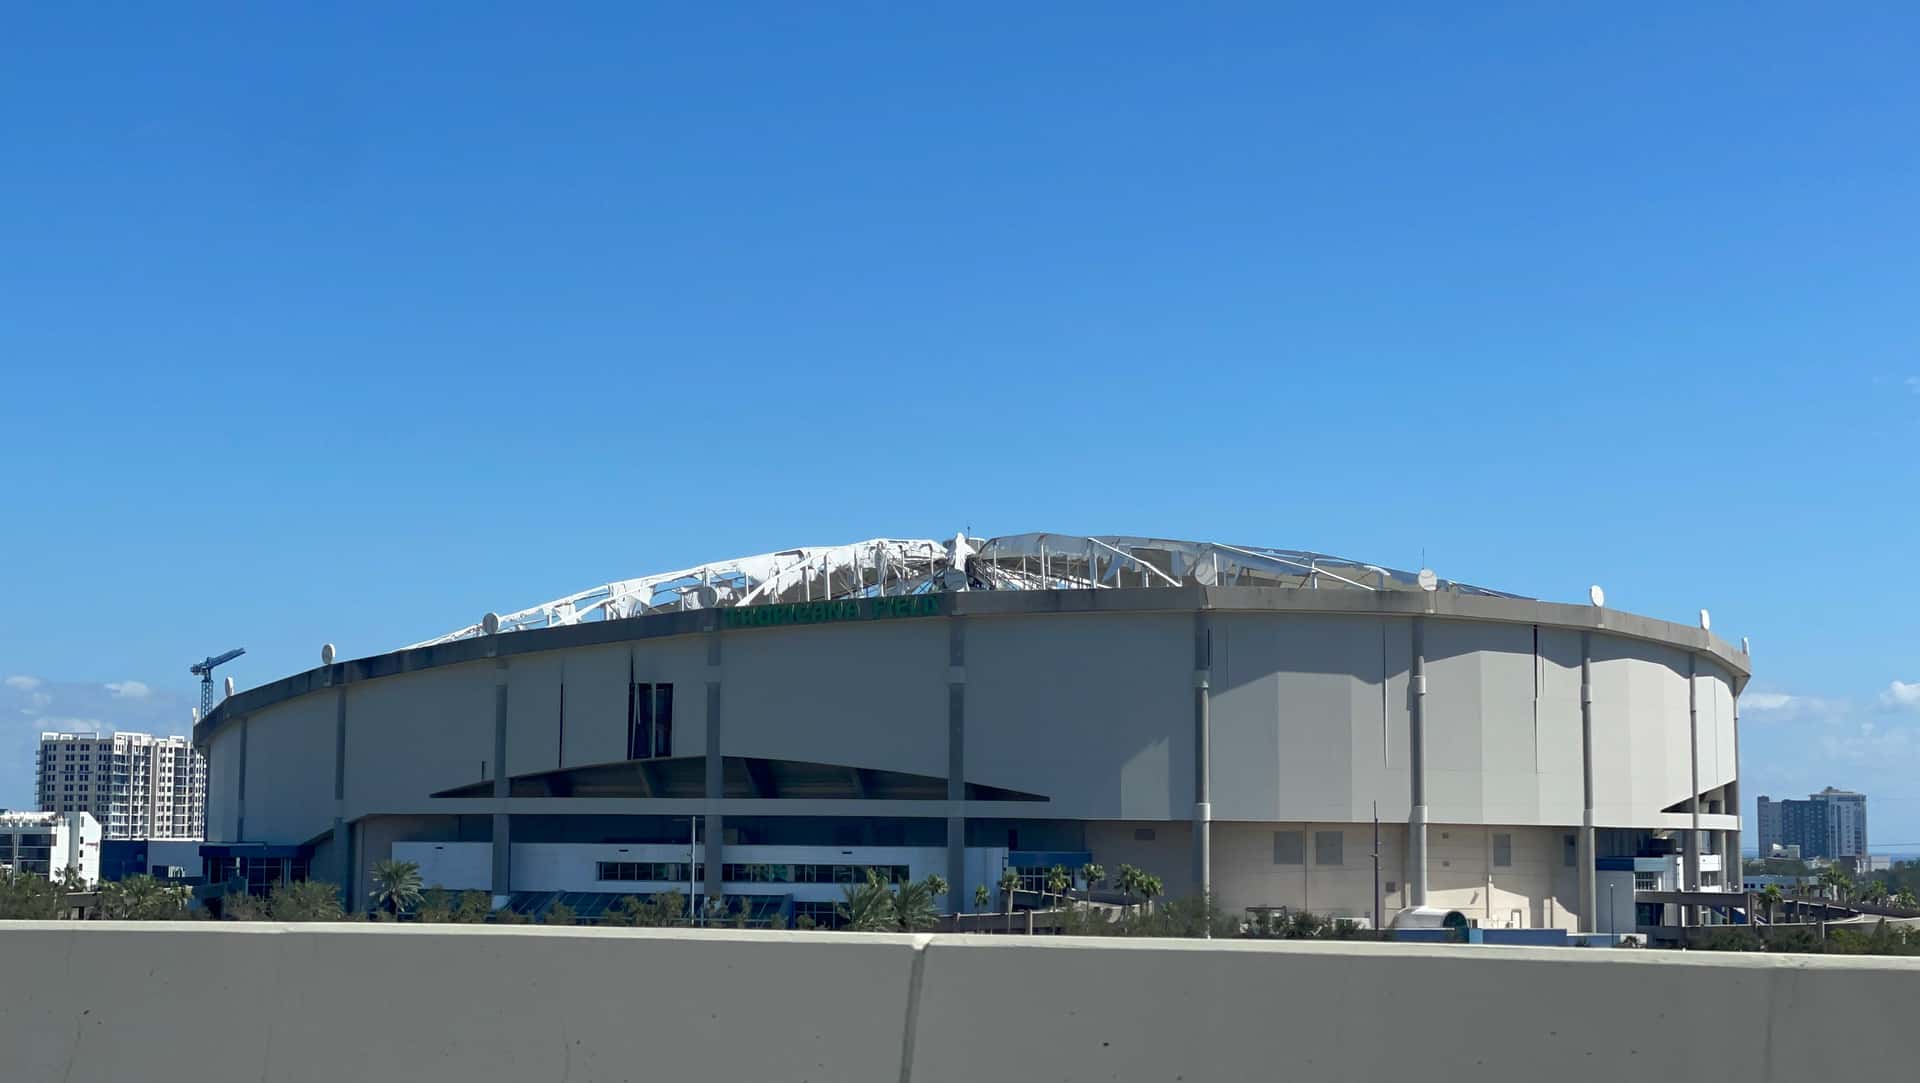
The state's recent major landfalls, severe as they were, did not hit the worst-case geography. A major hurricane moving directly up Tampa Bay, or across Miami-Dade and Broward at Category 4 strength, would generate insured losses on a scale that no combination of Florida-domiciled carrier surplus and current reinsurance program covers comfortably.
The carriers most exposed are precisely the newer, thinner-capitalized ones that returned to the state during the recovery and took Citizens policies out through depopulation. Those companies wrote the business that generated the improvement. They are also the ones with the least cushion.
Citizens shrinking to 255,000 policies reduces the assessment risk hanging over Florida consumers, which is genuinely good. It does not eliminate the mechanism. If private carriers fail in volume after a catastrophic storm, policies return to Citizens at exactly the moment Citizens is paying claims, and the assessment authority exists for that reason.
What the rate decreases actually deliver
A 7 percent average reduction from a base among the highest in the country still leaves a very high bill. Florida homeowners continue to pay more for property insurance in absolute dollars than homeowners almost anywhere else, and the improvement is in the rate of change rather than in the level.
The decreases are also narrower than the coverage suggests. Each applies to one carrier's book, reaches a homeowner only at renewal, and represents an average across a rating territory in which coastal and inland properties land on opposite sides. A homeowner insured by a company that did not file sees nothing.
Roughly 62,000 policies in a state with millions is a signal, not a volume event. Signals matter, and a company does not voluntarily reduce its price in a market it expects to deteriorate. But treating the signal as relief already delivered to Florida households overstates what has happened.
The clearest evidence that cost pressure has not resolved sits in the housing data. Florida's single-family median was $415,000 in August, up barely 1 percent, while inventory fell 13 percent. A market where prices are flat and supply is contracting is not a market where the cost of ownership has become comfortable.
The condominium problem nobody has solved
Everything above concerns single-family homeowners policies. The condominium segment is a separate crisis operating on a separate timeline, and it has received far less attention relative to its size.
The post-Surfside requirements for milestone structural inspections and funded reserves were the correct response to a building collapse that killed 98 people. They are also generating special assessments in aging coastal buildings that run into tens of thousands of dollars per unit, in buildings frequently occupied by retirees on fixed incomes.
Units in buildings with unfunded reserve deficiencies cannot obtain conventional financing, which removes them from the effective housing market while leaving them in the inventory statistics. That distortion is why Florida's reported supply overstates what a financed buyer can actually purchase.
No rate filing addresses this. The condominium problem is a capital expenditure problem wearing insurance clothing, and it will take a decade of assessments and construction to work through Florida's aging coastal building stock. The Legislature has adjusted timelines and funding rules at the margins without changing the underlying arithmetic.
What the 2027 session should not do
The 2027 legislative session will bring pressure to revisit the litigation changes. Consumer attorneys and some lawmakers argue the 2022 and 2023 statutes went too far in limiting policyholders' ability to challenge denials, and there is a serious case to examine in that complaint.
The examination should be narrow and evidence-based rather than a wholesale reversal. If specific categories of legitimate claims are being denied without effective recourse, that is a fixable problem that does not require reopening the fee-shifting framework that carriers price against. Reversing the reforms wholesale would reprice the market upward within a cycle.
The opposite temptation is equally worth resisting. Declaring the crisis over and moving on would leave Florida without the reserve building, building code enforcement and mitigation funding that determine how much damage a storm actually causes. Rate relief that arrives because losses are lower is durable. Rate relief that arrives because a bad year has not happened is not.
The most useful thing the Legislature could fund is mitigation. Roof strengthening, opening protection and water intrusion prevention reduce actual losses rather than redistributing them, and Florida's My Safe Florida Home program has consistently been oversubscribed relative to its appropriation.
What homeowners should do with this
Treat the current window as an opportunity rather than as a resolution. Rates are moving down and carriers are competing, which is the environment in which shopping a policy produces the best result. That window closes the moment a major storm resets reinsurance pricing.
Wind mitigation inspections remain the single highest-return action available to an individual homeowner, because Florida law requires insurers to discount for documented construction features. An inspection that captures roof deck attachment, roof-to-wall connections, secondary water resistance and opening protection can deliver savings exceeding any statewide filing.
Read the renewal declaration rather than the headlines. A policy can show a higher premium after an approved rate decrease if insured value rose, a credit expired or the form changed, and the only way to know is to compare the documents.
Flood coverage deserves separate attention, and the federal picture is unsettled. The National Flood Insurance Program is currently authorized only through December 11, having been extended alongside the continuing resolution. Florida holds a larger share of NFIP policies than any other state, and the program has now gone through 35 short-term extensions and five lapses since 2017.
The bottom line
Florida's insurance market has improved, and the people who did the legislative work deserve credit for the part they caused. Pretending otherwise would be as dishonest as the opposite claim.
But a market is not proven by the years it goes untested. It is proven by what happens when the event it was priced for actually arrives, and Florida's current market has been priced for a storm it has not yet seen.
The 2026 hurricane season has tracked below normal, consistent with NOAA's forecast, and runs through November 30. Below normal describes basin-wide storm counts, not landfall risk for any particular coastline, and Florida has been struck by major hurricanes in seasons that finished below average.
The right posture is neither triumph nor despair. It is to bank the current improvement, spend the calm building resilience rather than declaring victory, and remember that every favorable number in the state's filings has an implicit asterisk reading: assuming nothing hits Tampa Bay or Miami.
None of this argues for pessimism about Florida. It argues for precision. A market that has improved deserves to be described as having improved, and a market that has not been tested deserves to be described as untested. Conflating the two is how the state talked itself into complacency before, and the cost of that mistake was paid by homeowners rather than by anyone who made it.
Spotted an issue with this article?
Have something to say about this story?
Write a letter to the editor