Flood Insurance Deadline Arrives Sept. 30 With Florida Closings on the Line
The National Flood Insurance Program's authorization expires at 11:59 p.m. on September 30, and if Congress does not act, the program cannot issue new or renewal flood insurance policies, a stoppage that would disrupt residential real estate closings across Florida more than in any other state. Nine days remain on the clock.
The stakes are procedural rather than dramatic, which is part of why the deadline receives less attention than it warrants. Existing NFIP policies remain in effect until their expiration dates, including a 30-day grace period, so a lapse does not strip coverage from current policyholders. What it halts is the issuance of new and renewal policies, and that is what stops home sales.
Properties in designated flood zones with federally backed mortgages are required to carry flood insurance, which means a buyer who cannot obtain a policy cannot close. In a state with more NFIP policies than any other, a lapse converts a Washington procedural failure into thousands of stalled Florida transactions.
How the program got to another cliff
The NFIP has been operating on short-term extensions for years. Its last five-year reauthorization expired on September 30, 2017, and since then Congress has kept the program alive through a series of temporary measures rather than comprehensive legislation.
The current extension came on February 3, 2026, when the president signed legislation passed by Congress extending authorization to September 30, 2026. That measure accompanied the end of a partial government shutdown, which illustrates the pattern: the NFIP typically rides along with whatever larger fiscal vehicle is moving.
The reason reform keeps stalling is that the program's fundamental problems are politically unsolvable in isolation. The NFIP carries substantial debt, charges premiums that in many cases do not reflect actuarial risk, and insures repeatedly flooded properties. Fixing any of those means raising premiums on constituents who vote.
Reform legislation exists. The National Flood Insurance Program Reauthorization and Reform Act of 2025, introduced as H.R. 5484, represents one attempt at comprehensive treatment. Bills of that kind have been introduced in successive Congresses without passage.
Why Florida is the most exposed state
Florida holds more NFIP policies than any other state, a function of 8,400 miles of tidal coastline, low elevation, porous limestone geology and a population concentrated near the water. No other state's housing market depends as heavily on the program.
The geology matters more than most residents realize. Much of South Florida sits a few feet above sea level on limestone through which groundwater moves freely, meaning water rises from below during heavy rain as well as arriving from above. Rainfall that would drain in other states accumulates.
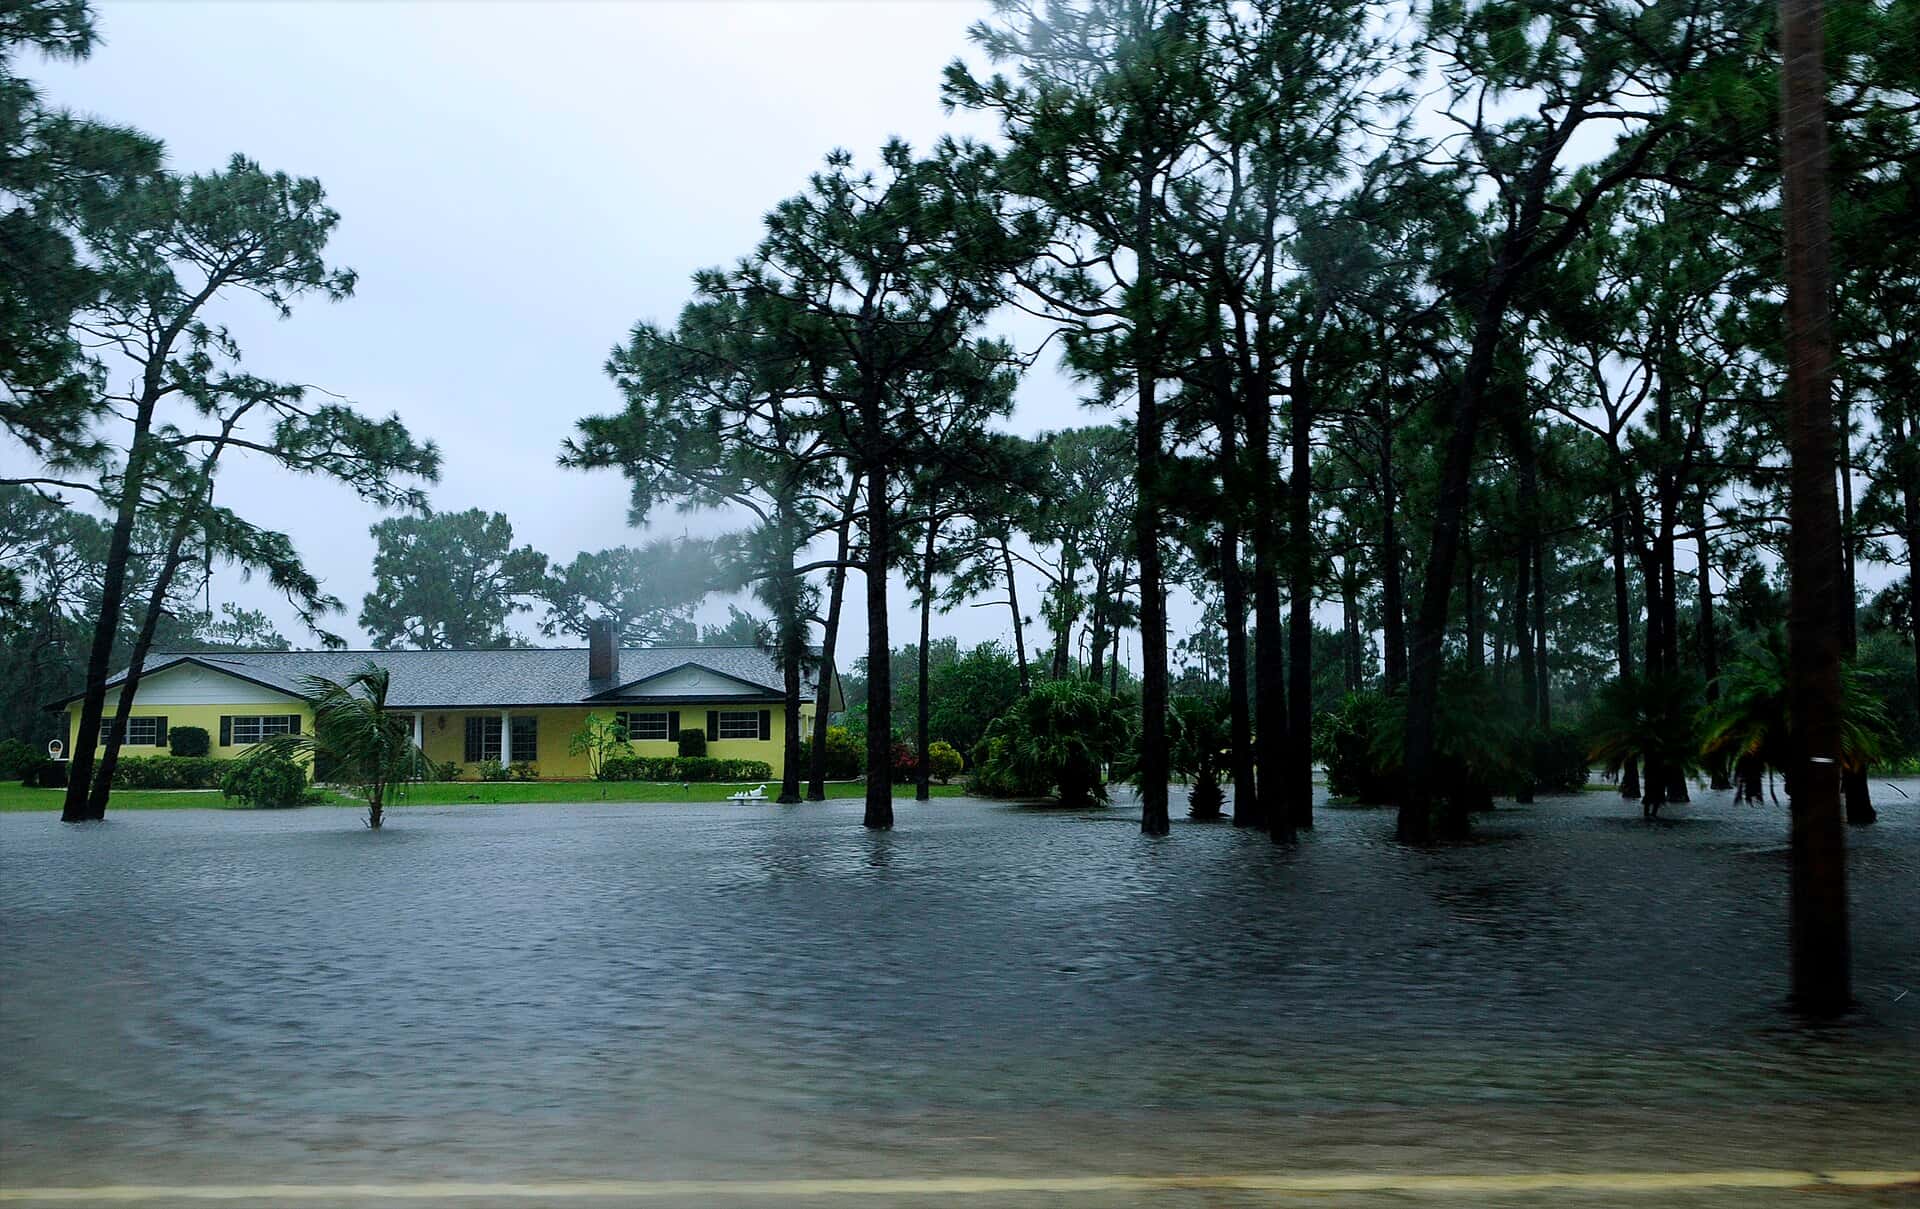
Recent weather illustrates the point. Parts of Palm Beach County absorbed more than 10 inches of rain over three days in mid-September from a non-tropical low over the eastern Gulf, with flood advisories cycling across the tri-county area. No named storm was involved.
That is the central misunderstanding about Florida flood risk. Homeowners associate flooding with hurricanes, and the 2026 Atlantic season has produced six named storms and no Florida landfall. The state flooded anyway, because flooding does not require a hurricane.
What a lapse would do to transactions
The mechanics are specific. A buyer purchasing a home in a Special Flood Hazard Area with a federally backed mortgage must obtain flood insurance before closing. If the NFIP cannot issue a policy and no private alternative is available or acceptable to the lender, the closing does not happen.
The disruption compounds. Real estate transactions chain together, with sellers depending on proceeds to fund their own purchases, and a single stalled closing can break a chain of four or five transactions. Rate locks expire, contracts face deadlines, and moving arrangements unravel.
Renewals present a separate problem. Policyholders whose coverage expires during a lapse cannot renew through the NFIP, and while the 30-day grace period provides a buffer, an extended lapse would eventually leave properties uninsured and potentially in violation of mortgage requirements.
Past lapses have been brief, lasting days rather than months, and Congress has consistently acted to restore authorization. That history is reassuring but not a guarantee, and the real estate industry has learned to treat each deadline as a genuine operational risk.
The private flood market alternative
Florida has developed the nation's most active private flood insurance market, driven by state legislation encouraging private carriers to compete with the NFIP. That market provides a genuine alternative for some properties and a partial cushion against a federal lapse.
Private flood policies frequently offer higher coverage limits than the NFIP's caps, which matters in a state with substantial high-value coastal property. For homes worth well above the federal limits, private coverage is often the better product independent of any lapse.
The limitations are real, though. Private carriers select risk, declining the properties with the worst loss histories, which are precisely the ones most dependent on the NFIP. Availability also varies by county and by proximity to the coast.
Lender acceptance is the practical constraint during a lapse. Private flood policies must meet federal criteria to satisfy mandatory purchase requirements, and while most established carriers issue compliant policies, the verification process adds time that a closing on a deadline may not have.
Where Florida's congressional delegation sits
Florida's delegation has historically been among the most engaged on NFIP issues, for the obvious reason that no state has more at stake. Members from both parties representing coastal districts have pursued reauthorization and have resisted premium increases that would fall heavily on Florida constituents.
That creates a recurring tension within each party. Fiscal conservatives concerned about the program's debt favor moving premiums toward actuarial rates; coastal representatives, including Florida Republicans, resist increases that would price constituents out of coverage. The result has been repeated short-term extensions.
The delegation's influence is substantial given Florida's size in the House. With a large congressional membership and two senators, the state can shape legislation when its members act together, and NFIP reauthorization is among the issues where they most often do.
The likely vehicle is appropriations. Congress faces a deadline to fund the federal government for fiscal year 2027, and an NFIP extension is expected to be attached to whatever measure emerges. That links flood insurance to a broader fiscal negotiation with its own failure modes.
The deeper policy problem
Short-term extensions preserve the status quo, and the status quo is a program with structural deficits insuring properties whose risk is rising. Sea-level rise, more intense rainfall events and continued coastal development all increase exposure while premiums lag.
Risk Rating 2.0, the NFIP's updated pricing methodology, moved premiums toward property-specific risk assessment rather than broad flood zone categories. The approach is more actuarially sound and produced significant increases for many Florida policyholders, generating political resistance.
Mapping is the other persistent controversy. FEMA's flood maps determine which properties face mandatory purchase requirements, and map updates that expand flood zones impose new insurance costs on homeowners who did not previously carry coverage. Local governments frequently contest those updates.
Mitigation offers the most defensible long-term answer. Elevating structures, installing flood vents, relocating mechanical equipment and improving community drainage reduce actual risk rather than redistributing its cost, and the NFIP's community rating system provides premium discounts to jurisdictions that invest in it.
What Florida homeowners should do now
Anyone with a closing scheduled in late September or early October should confirm flood insurance status immediately with their lender and insurance agent. Policies bound before the deadline are not affected by a lapse, and accelerating that step is the single most effective protection.
Existing policyholders should check their renewal dates. A policy renewing in October could be caught in a lapse, and the 30-day grace period provides time but not unlimited time. Agents can advise on whether early renewal is possible.
Homeowners outside designated flood zones should understand that they can purchase flood coverage voluntarily and that a significant share of flood claims come from properties outside high-risk zones. The mid-September rainfall across South Florida flooded properties that carry no mandatory purchase requirement.
The broader point is that standard homeowners insurance in Florida does not cover flood damage. That gap is the single most common and most expensive misunderstanding in Florida property insurance, and it becomes apparent to homeowners at the worst possible moment.
What Citizens and the state market cannot cover
Florida has spent years reconstructing its property insurance market, and the results have begun to show. Citizens Property Insurance Corporation approved rate recommendations reducing average personal lines rates for the first time since 2015, a statewide average decrease of 2.6%, and the carrier has shrunk from a peak above 1.4 million policies as private insurers absorbed risk back into the voluntary market.
None of that touches flood. Citizens writes windstorm and multiperil coverage, not the flood peril, and the state's reform legislation addressed litigation costs, claims practices and reinsurance rather than water that arrives at ground level. A homeowner with a Citizens policy and no flood coverage is uninsured for the mid-September rainfall that swamped Palm Beach County.
That division of coverage is a national convention rather than a Florida peculiarity, established when the NFIP was created in 1968 precisely because private insurers considered flood an uninsurable peril. The federal government took on what the market would not, and the market's reluctance has not fundamentally changed.
The practical consequence for Florida homeowners is that improvements in the state's property insurance market do not reduce flood exposure at all. Two separate policies, two separate markets, two separate regulatory regimes, and one homeowner who frequently believes the first covers the second.
What's next
Congress has nine days. The expected path is an extension attached to fiscal year 2027 appropriations, and the history of this program suggests reauthorization in some form is the likely outcome rather than an extended lapse.
Should a lapse occur, the duration would determine the damage. A few days would produce delayed closings and administrative scrambling; a lapse measured in weeks would meaningfully disrupt Florida's real estate market during a period when the market is already slowing under mortgage rates above 7%.
The longer question is whether Congress ever moves past short-term extensions. Nine reauthorization deadlines have come and gone since 2017 without comprehensive reform, and each extension postpones decisions about premiums, mapping and repetitive loss properties that grow more expensive the longer they wait. Florida, holding more policies than any other state, pays the largest share of that delay.
Spotted an issue with this article?
Have something to say about this story?
Write us a letterComments
No comments yet. Be the first to weigh in.
Related Coverage
U.S. Exports to Cuba Hit a Record $202.5 Million in August as Fuel Sold to Private Firms Makes America the Island's Top Supplier
12h ago
Seven Florida Cases Are Part of the Justice Department's Largest Push Yet to Strip Citizenship From Naturalized Americans
12h ago

Proposed 2030 Census Rule Could Cost Florida a House Seat, and Count Snowbirds as Floridians
13h ago
Alligator Alcatraz Is Closed, but Florida Is Still Chasing More Than $500 Million in Federal Reimbursement
17h ago