Orlando's Theme Park Balance Shifts as Universal's Epic Universe Reshapes the Market
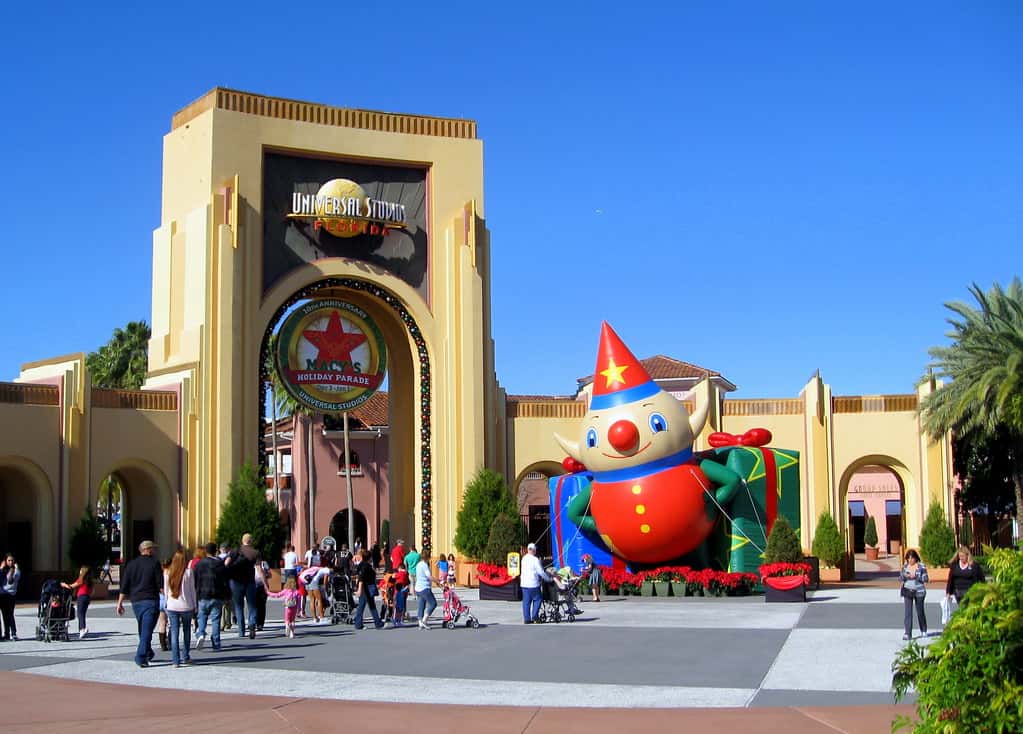
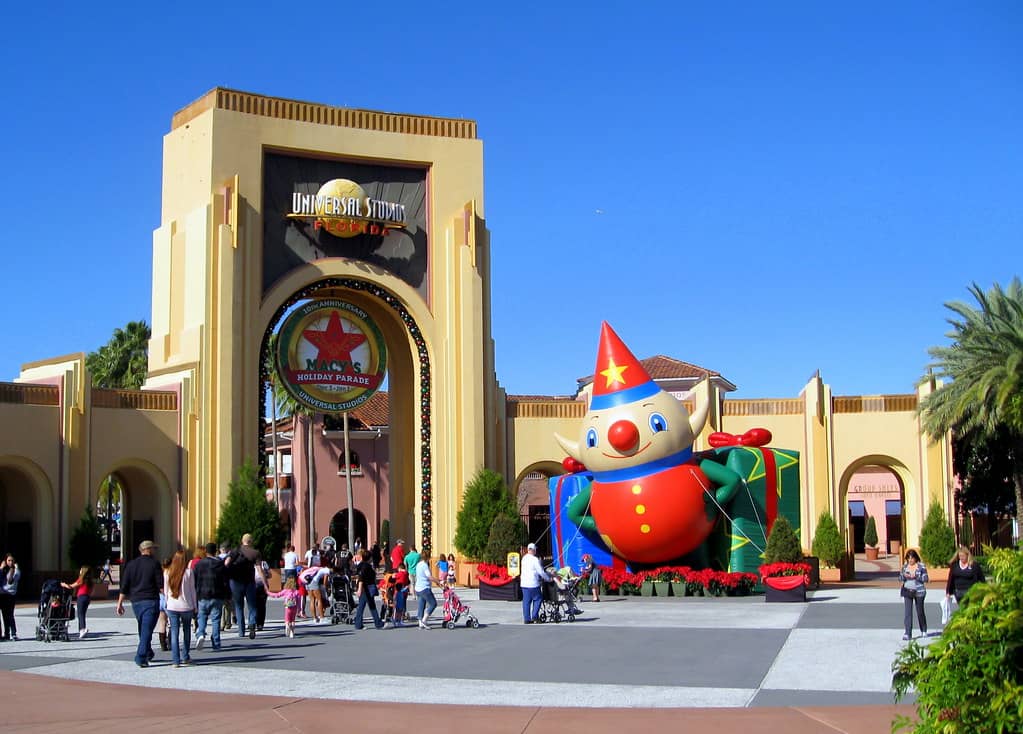
Orlando's theme park landscape looks materially different in 2026 than it did two years ago. Universal Orlando Resort now operates Epic Universe alongside its two existing parks, and the company's attractions took the top two positions in a major dark ride ranking for the second consecutive year, with Disney falling to third. Walt Disney World has responded with new offerings of its own, including The Magic of Disney Animation experience that opened September 14 at Disney's Hollywood Studios. The competition is reshaping how visitors plan Central Florida trips.
What has changed in the market
The addition of Epic Universe is the structural change behind everything else. Universal moved from a two-park resort to a three-park destination, which alters the arithmetic of a visitor's trip planning in a way that incremental attraction additions do not.
A two-park resort competes for a portion of a visitor's week. A three-park resort with substantial on-site hotel capacity can plausibly absorb an entire vacation, which changes Universal's position from a side trip within a Disney-anchored vacation to a destination in its own right.
The ranking results reinforce the shift. Universal holding the top two spots in the Best Dark Ride category for a second consecutive year, with Disney third, reflects the attraction technology investment the company has made and the critical reception of its recent additions.
Disney remains substantially larger in Orlando, operating four theme parks, two water parks, a large hotel portfolio and Disney Springs. Scale still favors Disney by a wide margin, and the ranking measures critical assessment of individual attractions rather than overall market share.
Disney's response
Walt Disney World has continued adding experiences across its parks. The Magic of Disney Animation, described as a family-friendly experience, opened September 14 at Disney's Hollywood Studios, reviving a concept the resort had operated in earlier years.
The company also ran seasonal programming through the summer, with activities across all four parks including character appearances, dance parties and games, plus dedicated experiences in Frontierland at Magic Kingdom and at Conservation Station in Animal Kingdom.
Seasonal programming and moderate-scale experiences serve a different purpose than headline attractions. They add reasons for annual passholders and repeat visitors to return without requiring the multi-year capital commitment a major ride represents.
Disney has announced a substantial pipeline of larger projects across its Orlando parks, and those will arrive over a period of years. The competitive question is what the market looks like while that pipeline is under construction.
What it means for Central Florida visitors
For visitors, the practical effect of intensified competition is more choice and more complexity. Planning a Central Florida trip now involves allocating days across two major resorts plus SeaWorld Orlando and Busch Gardens Tampa, with each operator offering multi-day ticket structures designed to capture more of a visitor's week.
That competition has generally been good for the visitor experience in terms of attraction quality, because both major operators are investing to differentiate. It has been less favorable on cost, as ticket pricing, express access products and hotel rates have all risen across the market.
Crowd distribution has shifted as well. A third Universal park absorbs attendance that previously concentrated across fewer venues, which can improve wait times across the market during moderate periods while peak holiday crowds remain substantial everywhere.
For Florida residents, annual pass products remain the primary access mechanism, and both operators structure resident pricing to encourage repeat local visitation during off-peak periods.
The economic stakes for Orlando
Tourism is the foundation of Central Florida's economy, and theme parks are its anchor. The Orlando, Kissimmee and Sanford metropolitan area added 11,900 jobs in the most recent monthly state labor report, second only to Tampa among Florida metropolitan areas.
Leisure and hospitality added 11,600 positions statewide over the year, and Central Florida accounts for a substantial share of that sector's employment base. Theme park operations, hotels, restaurants and the transportation network serving visitors all depend on attendance volumes.
Competition that expands the total market benefits the region more than competition that simply reallocates existing visitors between operators. The question for Orlando is whether a third Universal park draws additional visitors to Central Florida or divides the same visitors differently.
Early indications favor market expansion, because a destination that can fill a full week retains visitors who might otherwise split a Florida trip between Orlando and the coasts.
The broader Florida tourism picture
Central Florida's theme parks operate within a statewide tourism economy that also includes South Florida's beaches and urban attractions, the Gulf Coast, the Keys and a cruise industry that just set a record, with PortMiami crossing 10 million passengers in fiscal 2026.
Those segments interact. Visitors frequently combine an Orlando theme park stay with a cruise from Port Canaveral or PortMiami, and the operators have built packages around exactly that combination.
Florida's tourism marketing operates through Visit Florida at the state level alongside county-level tourism development organizations funded by bed taxes. Those organizations compete for visitors both against other states and, within Florida, against each other.
The state's visitor economy has been resilient through a period of higher interest rates and cost pressure, which is consistent with leisure and hospitality employment continuing to grow.
The cost question
The most persistent complaint about Central Florida theme parks concerns price. Ticket costs, on-site hotel rates, food pricing and paid line-skipping products have all risen substantially over the past decade, and a family vacation to Orlando now represents a significant financial commitment.
Both operators have moved toward tiered pricing structures that vary by date, which rewards flexible visitors with lower off-peak pricing while pushing peak-period costs higher. That structure spreads attendance but makes headline price comparisons difficult.
Paid express access products have become a substantial revenue line and a source of friction, with standby guests experiencing longer waits as a consequence. Operators have adjusted the structure of those products repeatedly in response.
Competition has not translated into lower prices, which is the outcome that surprises observers expecting a third major park to pressure pricing downward. Both operators have instead competed on product rather than price.
What comes next for the parks
Universal will focus on establishing Epic Universe's operating patterns through its first full years, including how it distributes attendance across the resort's three parks and how it integrates with the company's hotel portfolio.
Disney's announced pipeline of new attractions across its Orlando parks will arrive over a period of years, and each addition will be evaluated against what Universal has built. The competitive dynamic has raised the standard for what a new attraction must deliver.
SeaWorld Orlando and Busch Gardens Tampa continue to operate in the tier below the two majors, competing on roller coaster additions and on price positioning relative to the larger resorts.
The winter holiday period, which begins with Halloween programming and runs through the new year, is the market's peak season and will provide the first substantial test of how attendance distributes across the expanded market.
The workforce behind the parks
Central Florida's theme parks employ tens of thousands of people across operations, entertainment, food service, maintenance, engineering and hospitality, making them among the largest private employers in the region.
Opening a new park requires hiring at a scale that affects the regional labor market, and Universal's expansion drew workers from across Central Florida's hospitality sector. That competition for labor has consequences for wages and staffing at smaller employers in the region.
Union representation covers a substantial portion of the theme park workforce in Central Florida, and contract negotiations at the major operators have produced wage increases in recent bargaining cycles that set benchmarks across the regional hospitality market.
Housing costs remain the central pressure on that workforce. Orlando's rental market has tightened alongside population growth, and the distance between where park workers can afford to live and where the parks are located has grown, with commuting patterns reflecting that gap.
How visitors are planning differently
Trip planning for Central Florida has become substantially more complex than it was a decade ago. Reservation systems, date-based pricing, virtual queue arrangements and paid line-skipping products all require decisions before a visitor arrives.
That complexity favors experienced and research-intensive visitors over first-timers, and an industry of planning services and content has grown around the gap. Both operators have periodically adjusted their systems in response to complaints about difficulty.
Length of stay has shifted as well. A market offering seven parks between the two major operators plus SeaWorld and Busch Gardens supports longer visits, and hotel occupancy patterns reflect visitors staying more nights per trip.
International visitation, which historically made up a substantial share of Orlando's market, is sensitive to exchange rates and travel conditions, and its recovery and composition have shifted the visitor mix in ways operators price against.
The value question for families
The practical calculation for a family planning a Central Florida trip now involves deciding not merely which parks to visit but how many days each resort justifies. A three-park Universal resort makes a case for more days than a two-park resort did, and Disney's four parks have always made a case for most of a week.
Multi-day tickets reduce the per-day cost substantially at both operators, which rewards longer stays and penalizes visitors trying to sample both resorts in a short trip. That pricing structure is deliberate and it shapes itineraries.
Off-peak travel remains the single largest lever a budget-conscious family controls. Date-based pricing means the same trip can vary by hundreds of dollars depending on the week, and school calendars concentrate demand into predictable windows.
For Florida residents, annual passes with blackout dates offer the lowest effective cost per visit, and both operators structure resident products to fill capacity during periods when out-of-state visitation is lighter.
What's next
Attendance figures for the Orlando market are published annually by industry bodies with a considerable lag, which means the definitive data on how Epic Universe has affected the market will not be available for some time.
Both operators will announce their seasonal programming and any new attraction openings in the coming months, and those announcements shape visitor planning for the following year.
For Central Florida's economy, the relevant measure is total visitor volume and spending rather than which operator captures a larger share, and the region's employment data will continue to reflect that aggregate.
For visitors planning a trip, the practical consequence of the current competition is that Orlando now offers more than most vacations can absorb, which makes advance planning more necessary than it once was.
Spotted an issue with this article?
Have something to say about this story?
Write a letter to the editor