Disney and Universal Report Different Realities in the Orlando Theme Park Market
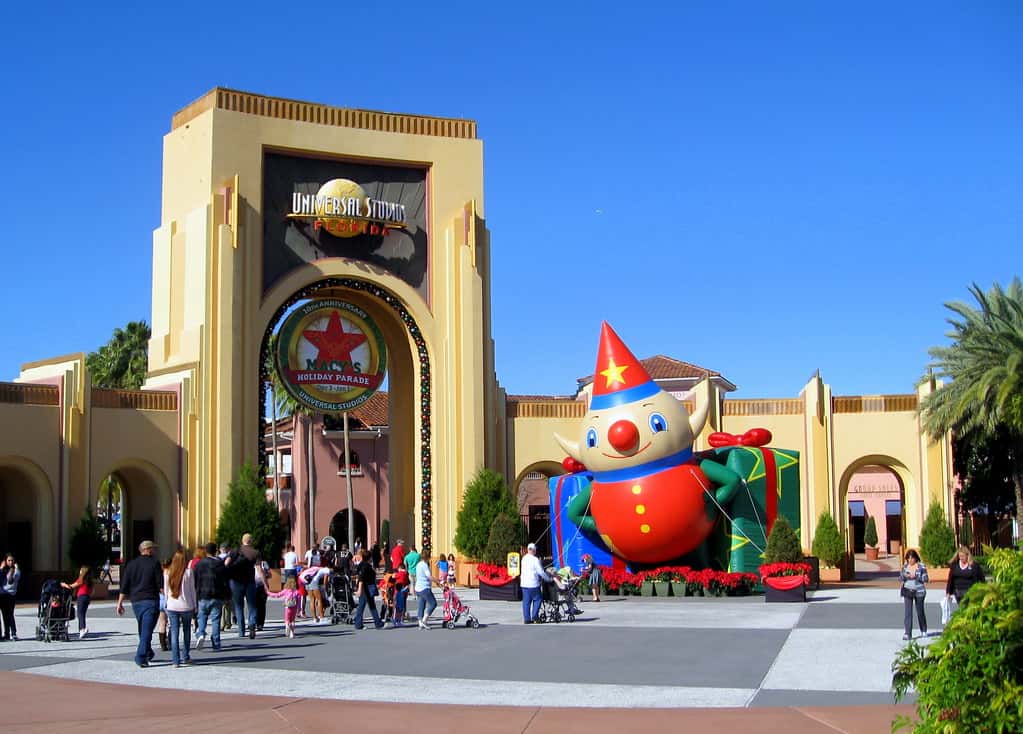
Orlando's theme park operators are describing very different conditions in the same market. Disney reported that combined attendance at Walt Disney World and Disneyland increased 3 percent over the summer, while Universal's co-chief executive said attendance across the broader Orlando market began to soften in June and that the trend continued into the third quarter. Epic Universe, Universal's newest Orlando park, has nonetheless been delivering against expectations, and the company reports it remains ahead of its position two years ago across attendance, per-capita spending, and guest satisfaction.
Two readings of one market
Disney's reported 3 percent increase covers combined attendance at Walt Disney World in Florida and Disneyland in California, which means the figure blends two distinct markets and does not isolate Orlando performance.
Universal's characterization was specific to Orlando and to the broader market rather than to its own parks alone. The company's co-chief executive described softening that began in June and persisted into the third quarter.
Those two statements are not necessarily contradictory. A market can soften overall while one operator gains share, particularly when that operator has invested heavily in new attractions and marketing.
Reporting conventions also differ. Public companies disclose attendance and spending metrics in ways shaped by segment reporting requirements, which limits direct comparison between operators.
What Epic Universe changed
Epic Universe opened as Universal's newest Orlando park and represented the largest single addition of theme park capacity in the market in decades. A new park of that scale changes the competitive structure rather than simply adding attendance.
Universal reports Epic Universe has been delivering against expectations and generating a strong guest response. The company states it remains ahead of its position two years ago across attendance, per-capita spending, financial performance, and guest satisfaction.
The park has also shifted visitor behavior in measurable ways. Multi-day Orlando trips that previously divided between Disney and Universal properties now have more Universal capacity to absorb, which changes length-of-stay patterns.
Crowd data through the late summer showed Epic Universe wait times dropping sharply in August and September, averaging 56 and 58 minutes respectively, with projections in the 35 to 45 minute range for the following two months.
The seasonal context
August and September are genuine off-season months for both Universal Orlando and Walt Disney World. School calendars pull families out of the market, and Florida's heat and afternoon storms discourage discretionary visits.
That seasonality means current wait times and crowd levels are not a useful indicator of underlying demand. Comparisons should be year over year for the same period rather than against summer peaks.
The softening Universal described began in June, which falls within the summer peak rather than the off-season. A decline beginning in June is a more meaningful signal than low September wait times.
Both operators structure pricing and capacity around this seasonal pattern, with discounting and annual pass availability weighted toward the slower months.
What is driving consumer behavior
Theme park visits are discretionary spending, sensitive to household budgets and consumer confidence. An Orlando trip for a family involves airfare or driving costs, multiple nights of lodging, park tickets, and food, a total that reaches thousands of dollars.
That price point competes directly with alternatives. Cruise demand has been exceptionally strong, with PortMiami welcoming its 10 millionth passenger of fiscal 2026 and Carnival Corporation reporting record revenue with occupancy above 100 percent.
The cruise value proposition, bundling lodging, meals, and entertainment into a single price, has proved attractive to budget-conscious families in a way that a theme park trip with separately priced components has not.
Interest rates affect the broader consumer picture. The Federal Reserve raised its benchmark rate on September 16, and households carrying variable-rate debt face higher costs that compete with vacation budgets.
Orlando's economic exposure
Central Florida's economy is more concentrated in tourism than any other major American metropolitan area. Hotels, restaurants, transportation, retail, and the supply chains serving them all depend on visitor volume.
Theme park employment is substantial in its own right, and the two major operators are among the region's largest private employers. Attendance softness affects hours and seasonal hiring before it affects permanent headcount.
Orange County's tourist development tax, levied on short-term lodging, funds convention facilities, venues, and tourism marketing. Collections track visitor volume directly, which makes park attendance a public finance variable.
The region's hotel inventory has expanded alongside the parks, including substantial capacity added in anticipation of Epic Universe. Occupancy in a softening market becomes a concern when supply has grown to meet expected demand.
Florida's broader tourism picture
The divergence between cruise strength and theme park softness is the most notable feature of Florida's current tourism data. Both sectors serve overlapping customer bases, and they are performing differently.
Beach and coastal tourism operates on different drivers, with drive-market visitation from within Florida and the Southeast providing a floor that destination attractions do not have.
The quiet 2026 hurricane season has removed a variable that typically disrupts fall tourism. No Florida landfall means no cancellations, no evacuation-driven closures, and no damage affecting fall bookings.
Florida's unemployment rate at 4.5 percent, above the 4.1 percent national average, reflects a state economy in which some sectors are expanding while others are flat, and tourism spans both categories.
What it means for visitors
A softer market generally benefits visitors. Shorter wait times, greater availability of dining reservations and hotel rooms, and more aggressive promotional pricing all follow from reduced demand.
Projected wait times in the 35 to 45 minute range at Epic Universe over the coming months represent a substantially better guest experience than peak-season conditions at a new park typically allow.
The fall shoulder season before the holiday period has historically offered the best combination of manageable crowds and reasonable weather in Orlando, and current conditions appear to extend that advantage.
Visitors should note that operators adjust capacity in slower periods, which can mean reduced operating hours and fewer attractions or entertainment offerings running on a given day.
What it means for the industry
For operators, a softening market tests the investment thesis behind recent capital spending. Epic Universe represented an enormous commitment made on the expectation of market growth.
Universal's position that it remains ahead of where it stood two years ago across multiple metrics suggests the investment is performing even as the broader market softens, which is the outcome the capital was meant to produce.
Disney's reported attendance increase indicates that the market's largest operator is not experiencing the same conditions Universal described, though the combined Florida and California figure obscures Orlando-specific performance.
Pricing strategy is where the divergence will show most clearly. Operators facing soft demand can defend attendance through discounting or defend per-capita spending by holding prices, and the choice reveals how each reads the situation.
How theme park economics work
Attendance is only one of two variables that determine a park's financial performance. Per-capita spending, covering food, merchandise, premium line-skipping products, and on-site lodging, has become as important as the number of people walking through the gate.
That shift has changed operator strategy. A park can report flat or declining attendance while improving financial results if per-capita spending rises enough, which is why public statements emphasizing one metric without the other are difficult to interpret.
Universal's framing, that it remains ahead of its position two years ago across attendance, per-capita spending, financial performance, and guest satisfaction, addresses all four at once, which is a broader claim than an attendance figure alone.
Capacity management is the operational lever. In slower periods operators reduce hours, run fewer entertainment offerings, and stage attractions differently, which preserves margin while changing the guest experience in ways visitors notice.
The annual pass question
Florida resident annual passes occupy an unusual position in Orlando economics. Local passholders visit frequently, spend less per visit than destination tourists, and provide a demand floor during periods when out-of-state visitation softens.
Operators manage that population carefully through blockout dates, tiered pricing, and periodic sales suspensions, balancing the revenue stability passholders provide against the capacity they consume during peak periods.
In a softening market, passholder demand becomes more valuable, and promotional activity aimed at Florida residents typically increases. That pattern is visible in pricing and pass availability during shoulder seasons.
For Central Florida households, that dynamic means the slower periods are when access is cheapest and crowds are lightest, which is the practical benefit of living in a market experiencing softness.
The hotel inventory overhang
Central Florida added substantial lodging capacity in anticipation of Epic Universe, on the reasonable expectation that a major new park would extend average trip length and draw additional visitors to the market.
Hotel development runs on long timelines, which means rooms conceived during a period of confident growth projections open into whatever market exists when construction finishes. That timing mismatch is a structural feature of the industry rather than a planning failure.
Occupancy in a softening market with expanded supply puts downward pressure on rates, which benefits visitors and squeezes operators. Orange County's tourist development tax, levied on short-term lodging, is collected on those rates and moves with them.
The vacation rental market adds another layer of supply that traditional occupancy data captures imperfectly. Central Florida has one of the largest concentrations of short-term rental inventory in the country, much of it aimed squarely at theme park visitors.
What's next
Quarterly earnings reports from both operators will provide more detailed attendance and spending data than public statements have. Those disclosures are the most reliable available measure of Orlando performance.
The holiday period from Thanksgiving through early January is the market's second peak, and performance during that window will indicate whether the summer softening was seasonal noise or a durable trend.
Central Florida's tourism economy has absorbed cycles before and recovered. The current question is narrower: whether a market that just added substantial capacity can fill it as consumer budgets tighten.
Spotted an issue with this article?
Have something to say about this story?
Write a letter to the editor